YOU LEFT THEM A HOUSE. GREAT. WHO PAYS TO BURY YOU?
YOU LEFT THEM A HOUSE. GREAT. WHO PAYS TO BURY YOU?
A Look at Wills, Probate, Bank Accounts, 401(k)s, Social Security—and Why Life Insurance Is Really About Cash When Your Family Needs It
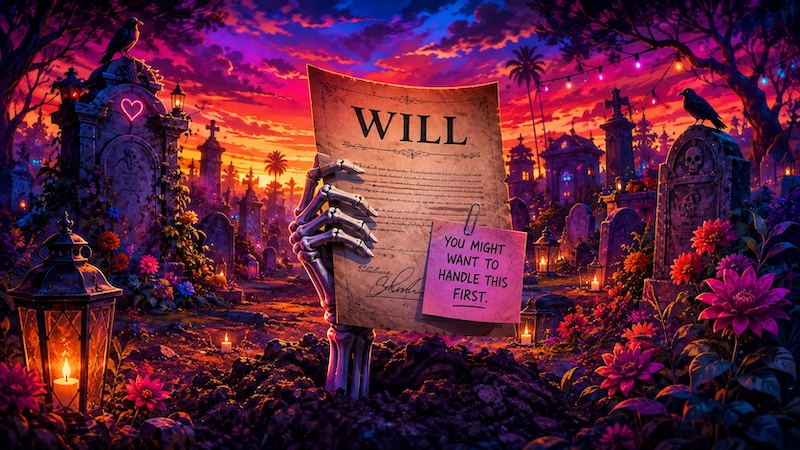
Look at the AI-created image I posted with this Parking Spot.
The guy is already dead.
He’s literally reaching out of the grave holding his will.
And somebody apparently stuck a note on it:
YOU MIGHT WANT TO HANDLE THIS FIRST.
😂
That’s pretty much estate planning in one picture.
People spend forty years accumulating things:
- A house.
- A retirement account.
- A car.
- Money in the bank.
- Maybe some investments.
Then they say:
“My kids will be fine. I’m leaving them everything.”
Maybe.
But here’s the question you can’t ask from the grave:
WHAT CAN THEY ACTUALLY USE THE WEEK YOU DIE?
Because owning assets and having usable cash are two very different things.
THE PERSON DIES. THE BILLS DON’T.
Your income can stop on Tuesday.
The electric bill doesn’t care.
Neither does:
- The mortgage.
- The car payment.
- The credit card.
- Property taxes.
- Insurance.
- Travel expenses for family coming to the funeral.
- Lost wages because somebody took time off work.
- The funeral home.
- The cemetery.
- The crematory.
- The lawyer.
- The court.
Death may stop your heartbeat.
IT DOESN’T STOP THE MAIL.
And that’s where people sometimes confuse wealth with liquidity.
You can die owning $500,000 worth of stuff and still leave your family scrambling for $5,000 in usable cash.
How do I know?
I’ve seen it firsthand.
“DON’T WORRY. THEY CAN SELL THE HOUSE.”
Great.
When?
- Tomorrow?
- Next Friday?
- Before the funeral?
The house may have equity.
It may also have:
- A mortgage.
- Repairs.
- Insurance.
- Property taxes.
- Personal belongings that need to be removed.
- Title issues.
- An executor or personal representative.
- Probate.
- Family members arguing about whether to sell it.
- A buyer who wants an inspection.
- A lender who wants paperwork.
- A closing date somewhere in the future.
A house can be a valuable inheritance.
A HOUSE IS NOT A CHECKING ACCOUNT.
Depending on how property is owned and state law, heirs may need estate documents or other proof establishing their legal right to inherited property before they can fully deal with it.
“BUT I HAVE A WILL.”
Great.
You probably should.
But here’s something people misunderstand:
A WILL DOESN’T AUTOMATICALLY MEAN “NO PROBATE.”
The Consumer Financial Protection Bureau explains that, depending on state law and how property is owned, heirs receiving a home through a will may still need to go through probate.
Probate is the legal process used to recognize a will, appoint the person responsible for the estate and distribute probate property.
A will can make that process clearer.
But it isn’t necessarily a trap door that makes the courthouse disappear.
A properly structured and funded revocable living trust is one tool people use to avoid probate for assets actually held in the trust.
Different tool. Different job.
And the judge isn’t standing around waiting for your relatives to show up the day after you die.
Probate can take time, and time can cost the living money.
YOUR WILL MAY BE A TERRIBLE PLACE TO HIDE YOUR FUNERAL PLANS
Here’s another one.
You carefully put in your will:
- I want to be buried.
- I don’t want to be cremated.
- I want this church service.
- I want this cemetery.
- I want this religious ritual.
- I want this song.
- I absolutely do not want Uncle Bob speaking.
😂
Wonderful.
Except there is a practical problem.
The American Bar Association has pointed out that a person may already be buried before a will is admitted to probate and an executor receives formal authority.
Think about that.
Your family could be trying to figure out what you wanted while the instructions are sitting inside a document nobody has seriously looked at yet.
MAYBE TELL SOMEBODY BEFORE YOU DIE.
Write it down separately. Make sure the right people know where it is. Have the uncomfortable conversation while you’re still available to answer questions.
That’s considerably easier than trying to communicate through a Ouija board later.
😂
You don’t want your relatives asking, “What was the name of that medium we saw on late-night television last year?”
“I’VE GOT MONEY IN THE BANK.”
Probably.
Can everybody else access it?
That depends on how the account is titled.
The CFPB notes that with a joint account, what happens after one owner dies depends on how the account is held: the money may pass to the surviving owner or to the deceased owner’s heirs.
That’s why planning matters.
“Dad had $40,000 in the bank.”
and
“I can legally use Dad’s $40,000 today.”
are not necessarily the same statement.
And if Dad never wanted his children on his accounts, showing up at the bank the morning after he dies isn’t likely to solve the problem. Being named executor in a will does not automatically mean the teller can hand you the money on demand; the bank may require proof of death, legal authority and other documentation.
“FINE. I’VE GOT A 401(K).”
Excellent.
But again:
WHO IS THE BENEFICIARY?
Retirement accounts have their own rules.
The U.S. Department of Labor explains that in most 401(k) and other defined-contribution plans, a surviving spouse generally receives the benefits when the participant dies, and naming somebody else may require the spouse’s consent.
So your will isn’t necessarily sitting above your retirement-plan beneficiary designation with a magic override button.
You need to know what the plan says.
You need to know who is named.
And somebody needs to know the account exists.
Are you seeing a pattern yet?
“SOCIAL SECURITY WILL HELP.”
It may.
Certain surviving spouses and family members can qualify for monthly survivor benefits.
But if you’re thinking there is some giant federal funeral check waiting for everybody, you may want to sit down.
As of 2026, the Social Security Administration says its lump-sum death payment is $255 for an eligible spouse or, in some circumstances, an eligible child.
$255.
I’ll give you a minute.
😂
That’s not nothing. It should buy some flowers.
But the local funeral director isn’t going to look at your $255 and say:
“Perfect. That covers everything.”
DEATH ALSO COMES WITH DEBT
Here is another unpleasant surprise.
Your debts don’t necessarily evaporate because you did.
The old saying is “death and taxes.” Unfortunately, the financial paperwork can keep going after the death part has already happened.
The CFPB explains that debts that must be paid are generally paid from the deceased person’s estate under applicable state law. Family members generally are not automatically personally responsible unless, for example, the debt was shared or state law makes them responsible.
So the estate may contain:
Assets.
And people standing in line wanting money from those assets.
DEATH ISN’T AS SIMPLE AS “THE KIDS GET EVERYTHING.”
NOW LIFE INSURANCE STARTS TO MAKE MORE SENSE
This is where I think people misunderstand life insurance.
They look at it as:
“I’m betting that I’m going to die.”
No.
You’re definitely going to die.
The insurance company already knows that.
😂
The real question is what financial problem your death creates for somebody who is still alive.
Life insurance can create something the house, furniture and family photographs cannot:
LIQUIDITY.
When a valid life-insurance claim is approved, the death benefit is paid according to the policy to the beneficiary or beneficiaries. A beneficiary generally has to submit a claim and required documentation, so this isn’t literally instant cash.
But compare that process with:
- Selling the house.
- Completing probate.
- Liquidating property.
- Untangling accounts.
- Finding buyers.
- Waiting for an estate distribution.
That’s why the real value isn’t merely:
“I LEFT THEM MONEY.”
It’s:
“I CREATED A SOURCE OF MONEY SPECIFICALLY BECAUSE I DIED.”
BURIAL INSURANCE ISN’T REALLY ABOUT THE DEAD PERSON
Smaller life-insurance policies are often marketed as final-expense or burial insurance.
The concept is simple.
You die.
Your beneficiary receives the policy benefit according to the contract and claim process.
That benefit can help with burial, cremation and other final expenses. The National Association of Insurance Commissioners identifies burial costs and continuing family expenses among the things consumers should consider when thinking about life-insurance needs.
But read the actual policy.
Policies differ. Coverage, exclusions, waiting periods or graded benefits can vary, so nobody should assume every final-expense policy works the same way from day one.
THE CONTRACT MATTERS.
And this is where people sometimes compare the wrong things.
Burial insurance isn’t supposed to win a Wall Street investment contest. Its job is to help create money for the people who are still alive when you aren’t.
You may have plenty of money in a bank account, a house or investments. But if your family can’t get to it when the funeral home wants to be paid, it might as well be buried in the backyard with a map saying:
“You’ll find this in a month or two. In the meantime, good luck.”
BUT THE FUNERAL MAY BE THE SMALL PART
Suppose the funeral costs $8,000.
Fine.
What happens the month after the funeral?
What if Dad was producing $5,000 a month of household income?
Dad dies.
The funeral ends.
Everybody goes home.
DAD’S PAYCHECK DOESN’T COME BACK MONDAY.
Now Mom still has:
- The mortgage.
- Utilities.
- Food.
- Insurance.
- Taxes.
- Transportation.
- Medical bills.
- Maybe children.
- Maybe grandchildren.
- Maybe debt.
- Maybe an attorney.
It may be months before the family fully understands what Dad owned, where everything is and what can legally be accessed.
That’s why life insurance isn’t simply death money.
It can be time money.
Money that gives the surviving family time to breathe before making irreversible decisions.
YOUR FAMILY DOESN’T NEED ONE DOCUMENT
This may be the biggest point.
People want one magic answer:
- “I have a will.”
- “I have life insurance.”
- “I made a trust.”
- “My daughter is on my bank account.”
- “I named somebody on the 401(k).”
Wonderful.
Those things don’t necessarily replace one another.
A will does one job.
A trust can do another.
Beneficiary designations do another.
Life insurance does another.
Retirement plans have their own rules.
Bank accounts have their own ownership structures.
Funeral instructions solve a completely different problem.
THE PLAN IS THE SYSTEM—NOT ONE PIECE OF PAPER.
AND THAT’S WHAT THE DEAD GUY IN THE PICTURE IS TRYING TO TELL YOU
Look at him again.
He’s holding the will.
He’s already in the cemetery.
Bit late for revisions.
😂
And the note says:
YOU MIGHT WANT TO HANDLE THIS FIRST.
I think he’s right.
Everybody knows two things are inevitable:
DEATH.
TAXES.
Yet people can spend more time planning a one-week vacation than planning what happens to decades of accumulated money, property, accounts, insurance, debt and personal wishes when they die.
Then somebody else gets handed the mess.
MAYBE THE BEST LEGACY ISN’T JUST WHAT YOU LEAVE
Maybe it’s how easy you make it for the people you love to deal with what you left.
A house is great.
A retirement account is great.
Investments are great.
A will is great.
A trust may be appropriate.
Life insurance may be appropriate.
Clear burial instructions may be appropriate.
Cash may be extremely appropriate.
Depending on your situation, you may need some combination of them.
DON’T JUST LEAVE ASSETS.
LEAVE INSTRUCTIONS.
LEAVE ACCESS.
LEAVE LIQUIDITY.
LEAVE LESS OF A MESS.
Because your family is already going to be dealing with one fairly significant problem.
YOU’RE DEAD.
😂
Maybe don’t make them solve twenty financial mysteries at the same time like you left them in the middle of a game of Clue. They may already know how you died. That’s only the first problem that needs to be figured out.
THINKING ABOUT MONEY BEFORE AND AFTER THE GRAVE?
This Parking Spot is about what can happen financially after you die.
There is another side of the equation:
WHAT DO YOU DO WITH THE MONEY WHILE YOU’RE STILL ALIVE?
If you’re thinking about retirement income, financial planning and how annuities may fit into the picture, visit SalesFreak.com and take a look at:
ANNUITY IN A BOX
Annuities and life insurance are different products, and neither replaces appropriate legal, tax, insurance or estate-planning advice.
But the common idea is simple:
MONEY WORKS BETTER WHEN YOU DECIDE WHAT IT’S SUPPOSED TO DO BEFORE YOU NEED IT.
And stay tuned here at GraveFreak.com.
There are a lot more financial problems hiding around the grave than most people realize.
THE DEAD GUY CAN’T FIX THE PLAN.
YOU STILL CAN.
GOT SOMETHING AROUND THE GRAVE WORTH PARKING?
You don’t have to sell insurance, write wills or work in a funeral home to have something worth sharing here.
A family lesson. An estate-planning mistake. A burial story. A financial warning. Something you learned after somebody died. A service you provide. A product people should know about.
If it genuinely belongs somewhere around the grave, give it its own Parking Spot.
A standard GraveFreak.com Parking Spot is $7 and gives your subject its own full-page place to live.
This Parking Spot is general educational commentary, not individualized legal, tax, financial or insurance advice. Probate rules, account access, beneficiary rights, insurance terms and estate procedures vary by state, contract and personal situation. Review your own documents and consult appropriate licensed professionals when needed.
(Illustrations used in this listing are conceptual editorial images created for storytelling purposes.)